What is the scope and industry significance of the Military Ground Robots Market?
Our analysis indicates the Military Ground Robots Market represents a critical paradigm shift in modern defense technology, valued at $4.80 Billion in 2026. This sector encompasses unmanned ground vehicles utilized across defense and homeland security to minimize personnel risk during high-threat engagements. The industry is rapidly evolving through the integration of advanced sensors and autonomous navigation systems designed to handle complex battlefield terrain and asymmetrical warfare challenges.
What are the key market drivers, restraints, challenges, and opportunities shaping the Military Ground Robots Market?
The Military Ground Robots Market industry trends are heavily propelled by rising global defense budgets and the imperative to reduce soldier casualties in urban combat. However, high development costs and strict military certification standards act as primary market restraints. Significant opportunities lie in the integration of artificial intelligence for autonomous operations, allowing industry leaders like Lockheed Martin Corporation and General Dynamics Corporation to pioneer next-generation tactical mobility platforms.
Emerging trends and growth patterns in the Military Ground Robots Market
The transition toward fully autonomous operation modes stands out as a transformative growth pattern across the Military Ground Robots Market. Defense contractors are increasingly prioritizing multi-mode mobility and adaptive terrain hybrid robots over traditional remote-controlled units. This technological shift directly addresses demands for reduced operator cognitive load and enhanced operational tempo in contested electronic warfare environments where communication links are frequently jammed.
How did the COVID-19 pandemic affect the Military Ground Robots Market and shape its recovery trajectory?
Supply chain disruptions and component shortages temporarily delayed advanced sensor procurements during the pandemic. Nevertheless, our research shows that post-COVID recovery accelerated digital transformation and automated manufacturing initiatives. Defense ministries prioritized contactless logistics and remote surveillance systems, fueling robust baseline demand for systems engineered by Teledyne FLIR LLC and QinetiQ Group plc.
Competitive benchmarking and strategic dynamics in the Military Ground Robots Market
Market concentration in the Military Ground Robots Market is moderately high, dominated by prime defense contractors alongside agile technology innovators like AeroVironment Inc. and Overland AI Inc. Strategic dynamics involve aggressive mergers, acquisitions, and joint ventures aimed at securing lucrative government contracts for unmanned systems. Companies leverage proprietary mobility architectures to capture market share across specialized payload and operation mode segments.
Executive summary of the Military Ground Robots Market report
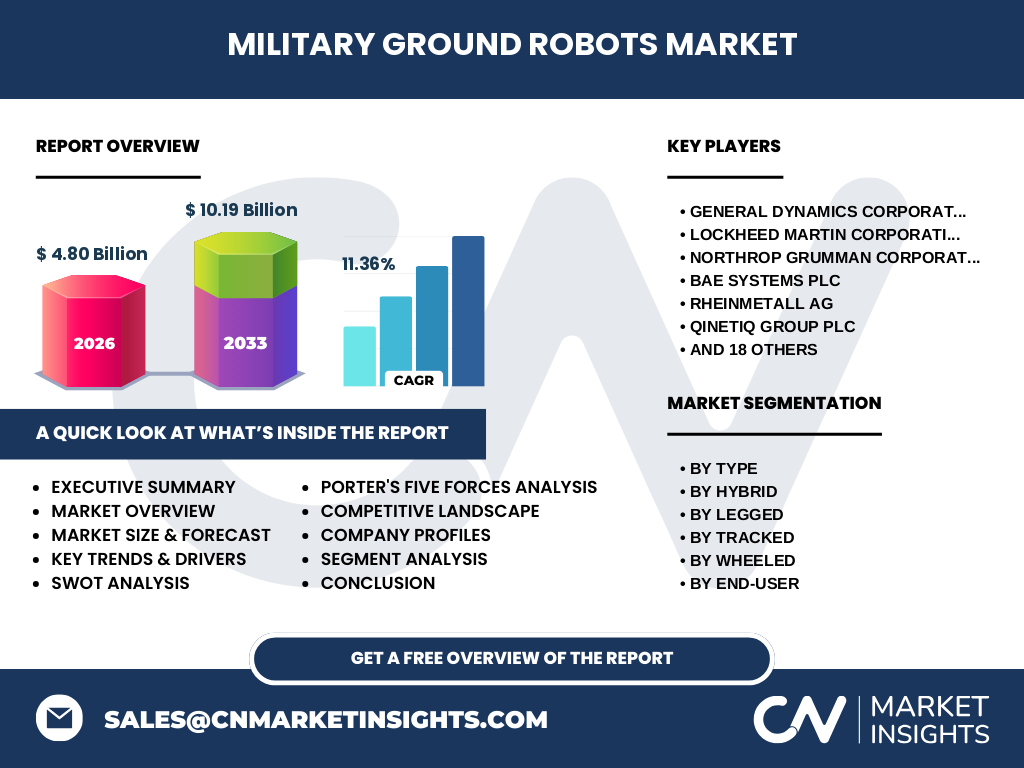
Our comprehensive Military Ground Robots Market analysis forecasts robust expansion from $4.80 Billion in 2026 to $10.19 Billion by 2033, surging at a compound annual growth rate of 11.36%. Growth is anchored by escalating investments in autonomous intelligence, surveillance, and reconnaissance (ISR) platforms. Defense modernization mandates across North America and Europe are driving unprecedented demand for tracked and wheeled tactical assets.
Market forecast trajectory from 2027 to 2033
The Military Ground Robots Market market size is projected to scale aggressively, reaching $10.19 Billion by 2033 from its 2026 baseline. Sustained double-digit expansion at an 11.36% CAGR reflects accelerated adoption of autonomous and semi-autonomous systems. This trajectory is supported by long-term military procurement planning and rising demand for heavy load carrier robots and explosive ordnance disposal solutions.
Segmentation analysis across product types, end-users, applications, operation modes, and payloads
The Military Ground Robots Market is segmented comprehensively to address diverse tactical requirements:
- By Type: Wheeled, Tracked, Legged, and Hybrid platforms.
- By End-User: Defense and Homeland Security.
- By Application: ISR, EOD, Transportation, Combat Support, and Search and Rescue.
- By Operation Mode: Autonomous, Semi-Autonomous, and Remote-Controlled.
- By Payload Capacity: Under 100 Kg, 100 Kg to 500 Kg, and Above 500 Kg.
Geographic distribution and regional performance in the Military Ground Robots Market
Regional performance varies significantly, with North America retaining the dominant revenue share owing to substantial defense R&D budgets and early adoption by agencies like the U.S. Department of Defense. Meanwhile, the Asia-Pacific region exhibits the fastest growth rate, driven by border security modernization programs in nations like South Korea and India, where localized terrain constraints favor specialized tracked and legged platforms.
In-depth regional review of high-potential territories
European markets are experiencing renewed urgency in unmanned ground systems procurement amid shifting geopolitical security dynamics. Regulatory compliance with stringent defense standards shapes local procurement. Simultaneously, the Middle East represents a lucrative zone for combat support and explosive disposal tracked robots, with key regional actors like EDGE Group investing heavily in indigenous robotic capabilities and advanced sensor payloads.
Company profiles and strategic positioning of key market participants
Industry leaders maintain distinct competitive moats through specialized engineering and global supply chains. Northrop Grumman Corporation and BAE Systems plc focus on heavy tactical integration, while Elbit Systems Ltd. and Israel Aerospace Industries excel in tactical ISR and remote-controlled combat solutions. Meanwhile, specialized innovators like Hanwha Aerospace Co. Ltd. and Hyundai Rotem Company drive advancements in robust ground mobility.
Porter's Five Forces analysis of the competitive landscape
Our analysis reveals moderate-to-high supplier power due to the proprietary nature of military-grade sensors and hardened processors. Threat of new entrants remains low given massive capital requirements and stringent military qualification barriers. Rivalry among established primes is intense, driving continuous technological innovation in autonomous navigation and multi-mode mobility systems to capture restricted defense budgets.
SWOT analysis of the Military Ground Robots Market
Key strengths include advanced autonomy and reduced soldier fatality risks during combat operations. Weaknesses involve high maintenance overhead and vulnerability to electronic jamming. Opportunities abound in integration with uncrewed aerial systems for joint multi-domain operations. Threats center around stringent export controls like ITAR and rapid technological obsolescence of proprietary electronic components.
Value chain analysis from raw materials to end-users
The value chain begins with raw material suppliers providing rare-earth elements and aerospace-grade aluminum, progressing to component manufacturers producing ruggedized microprocessors and LiDAR sensors. Tier-1 integrators—such as Kongsberg Gruppen ASA, L3Harris Technologies Inc., and Rheinmetall AG—assemble complete platforms before rigorous military testing and deployment to defense end-users.
Investment insights and high-potential areas for strategic deployment
Investors should target developers of autonomous navigation software and adaptive terrain hybrid robots, as software-defined capabilities represent the highest margin sectors. Funding priorities should also focus on power-efficient actuation systems and secure mesh networking technologies designed for contested electromagnetic battlefields, where firms like Thales S.A. hold competitive advantages.
Conclusion and key takeaways for stakeholders
The Military Ground Robots Market offers compelling growth prospects, projected to hit $10.19 Billion by 2033. Stakeholders must pivot toward software-driven autonomy, multi-mode mobility, and robust supply chain resilience. Organizations that successfully navigate defense certification protocols and integrate artificial intelligence will capture disproportionate market share in this expanding defense sector.
Research methodology for baseline estimates and data triangulation
Our research methodology combines rigorous primary stakeholder interviews with defense procurement officials, C-suite executives, and prime contractor product managers. This qualitative insight is triangulated against secondary macroeconomic indicators, defense registry data, government budget allocations, and trade filings to establish reliable baseline estimates for market size and segment growth trajectories.
Scope of the report, coverage parameters, and analytical limitations
This report covers global developments in the Military Ground Robots Market from 2027 to 2033, analyzing wheeled, tracked, legged, and hybrid systems across defense and homeland security end-users. Limitations include restricted access to classified black-budget military programs and rapid geopolitical shifts that may alter defense spending priorities across specific sovereign territories.
Recent developments, company announcements, and strategic partnerships
Recent industry momentum is defined by strategic partnerships between defense primes and AI startups. Notable moves include joint development agreements for autonomous resupply vehicles and new product launches featuring advanced explosive ordnance disposal tracked robots. Companies such as Leonardo S.p.A. and Singapore Technologies Engineering Ltd continue to expand their global footprint through collaborative cross-border defense modernization contracts.